AI Agents and the Future of Financial Regulation
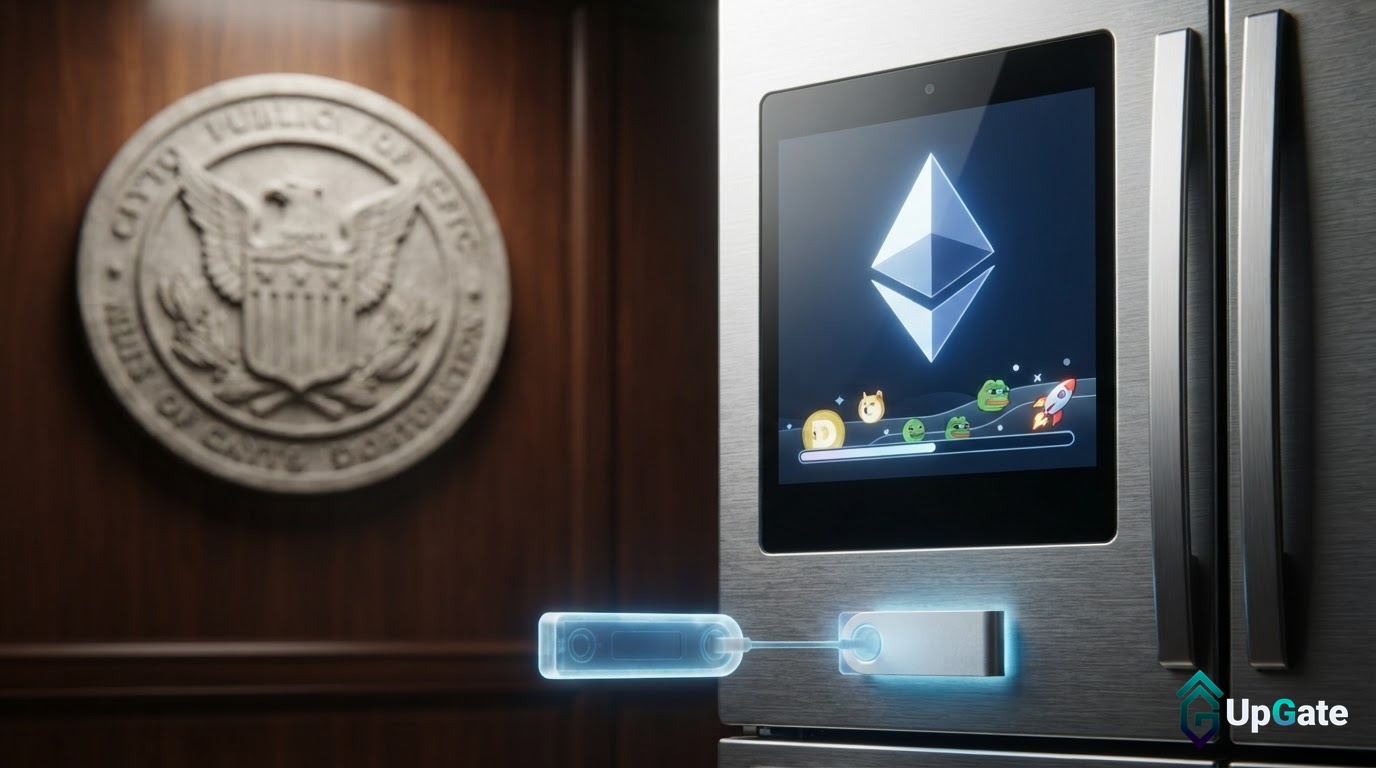
Washington D.C. – The notion of a refrigerator using staked Ether to buy groceries or even issue its own meme coin is no longer science fiction, according to Michael Selig, Chairman of the U.S. Commodity Futures Trading Commission (CFTC). Speaking at the inaugural Frontier Forum in Washington D.C. on Wednesday, Selig painted a vivid picture of the regulatory challenges posed by increasingly autonomous artificial intelligence. His concern extends beyond hypothetical appliances to the fundamental question of how existing financial rules, designed around identifiable human participants, will adapt when AI agents can hold assets and execute trades independently.
Selig invoked a quote from former U.S. President Donald Trump, referring to such technology as “super intelligence” (SI) because it is “not artificial” but a genuine technological leap akin to the printing press, steam engine, or the internet. This perspective comes as younger investors are already integrating AI into their financial decision-making. A September survey revealed that 79% of U.S. millennial investors and 77% of Gen Z investors have used or are willing to use AI for investment selection and adjustments.
The CFTC’s regulatory framework, Selig explained, is built on the premise of “identifiable market participants.” Every registration, reporting, and accountability obligation assumes a responsible individual or entity behind it. However, autonomous software is destabilizing this assumption. He posed a series of critical questions: Should developers of AI agents be registered if their agents identify trading opportunities and execute orders on behalf of users? Who is liable when an agent malfunctions and causes losses? How can regulators ascertain who an agent, or a group of agents, is trading for? He even raised the possibility of a new “know-your-agent” (KYA) mechanism.
These questions are difficult to answer because current rules assign responsibility based on “who placed the order,” but when an agent places an order, the entity pressing the button and the software making the decision are not the same. When an agent’s behavior is determined by model weights and data, traditional human-centric registration and reporting systems create loopholes.
Selig highlighted two key impacts of AI. On the positive side, super intelligence can process information with far greater speed and accuracy than the human brain, potentially democratizing risk management tools previously accessible only to large institutions, making them available to smaller traders and businesses. The downside lies in autonomy: agents may react to market conditions in unexpected ways. Furthermore, agents using similar models can exhibit highly correlated trading behavior, amplifying volatility when they move in the same direction. The increased speed of order placement also makes market surveillance and risk control more challenging to keep pace with.
These concerns are not isolated. Yat Siu, Chairman of Animoca Brands, has previously warned that if a thousand people ask an AI the same trading question, they will receive nearly identical answers, creating a new source of systemic risk through this uniformity. The Bank of England’s Financial Policy Committee has also cautioned that widespread use of similar models in the market could amplify market shocks.
While regulators are still grappling with these questions, exchanges are already deploying the tools. Coinbase launched Agentic Wallets in February, allowing AI agents to make payments and execute trades within user-defined limits. Binance, in March, introduced AI Agent Skills, offering market data and tools for order placement and management of spot positions. Agent-driven trading is not a future concept but an existing product line, currently managed primarily through user-side limits and permission settings rather than a robust framework for agent identity and accountability.
The core issue is not whether AI will place orders, but rather who is acting on whose behalf and according to what rules. In September, Selig’s focus on tokenization centered on 24/7 markets and real-time collateral movement. A month later, his discussion shifted to agent identity and responsibility, indicating a progression from “how assets get on-chain” to “how actions are attributed.” For retail-dominated markets, this presents a structural risk: if the agents of many individuals rely on the same models and signals, the market could experience synchronized congestion similar to that previously caused by institutional quantitative trading, with retail investors often being the slowest to exit.
Another concern is the breakdown in the chain of accountability. When an agent errs, users can claim they only set parameters, and developers can state they only provided tools, leaving no single party clearly defined by current regulations. This is precisely why concepts like KYA are being proposed. The questions the CFTC is now asking are ones that all future financial scenarios involving agents making decisions on behalf of humans will need to answer.
Two key developments to watch are: first, whether the CFTC will translate these questions from the Frontier Forum into concrete rule proposals, particularly regarding registration obligations and liability for agent developers; and second, whether exchanges will preemptively introduce self-regulatory measures, such as requiring agents to maintain auditable records of user authorization, tradable assets, and risk control limits. Whoever defines the identity of agents first will shape the division of labor in the next iteration of financial infrastructure.